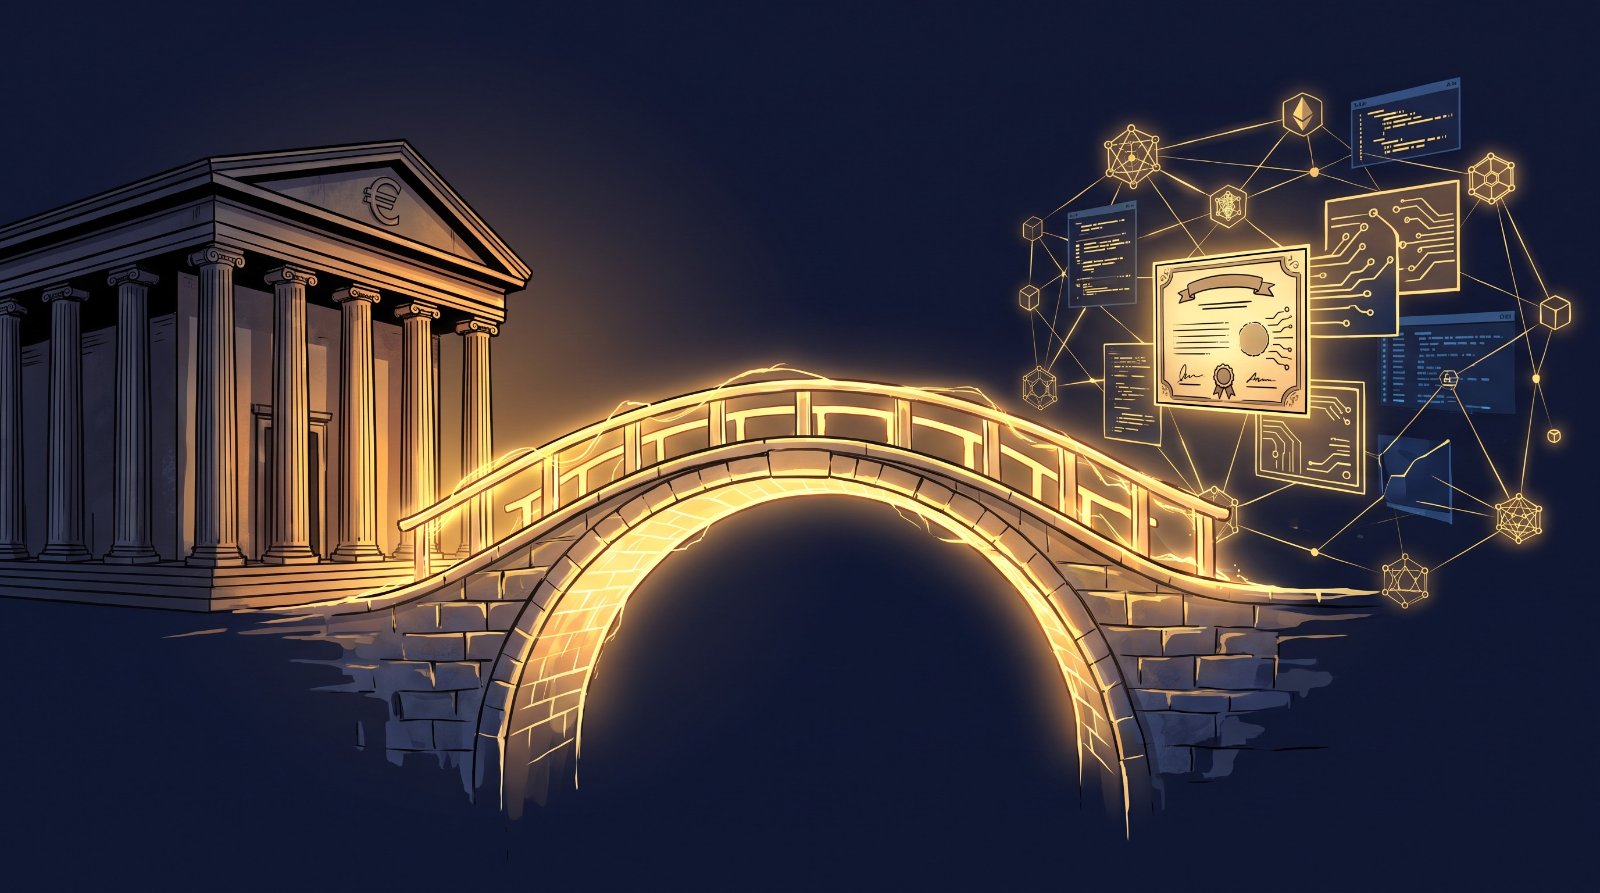
For years, tokenisation projects in Europe ran into the same wall. Putting a bond or a fund share on a distributed ledger turned out to be the easy part. The harder question was what the buyer pays with. The options on the table were private money: a stablecoin, where you carry the issuer's risk, or a tokenised bank deposit, where you carry the risk of that bank. For a treasury desk moving hundreds of millions, neither is a comfortable answer.
On 21 September 2026 the European Central Bank gave a third answer. Pontes, Latin for "bridges", links market DLT platforms to the Eurosystem's TARGET Services, so that DLT-based wholesale transactions can settle in central bank money, either via cash tokens on the platform or directly in T2.
What actually went live
According to the ECB, Pontes is open to entities with T2 access, authorised central securities depositories and DLT settlement operators, overseen payment system operators, central counterparties and eligible credit institutions. It uses a hash-link protocol so that the asset leg and the cash leg of a delivery-versus-payment trade either both settle or neither does.
Early participants reported at launch include Deutsche Bank, Santander and Clearstream. Operating hours are still conventional: 8:00 to 16:00 CET on business days. The groundwork was laid in the Eurosystem's 2024 exploratory work, which ran more than 50 trials with 64 participants and processed around EUR 1.5 billion.
The ECB is also putting its own balance sheet behind the idea. It plans to allocate a small share of its roughly EUR 23 billion own-funds portfolio to tokenised public sector and supranational debt settled through Pontes. No amount has been disclosed.
Why this matters more than the ledger
Christine Lagarde described Pontes as "a digital euro made available for banks" (CoinDesk). That framing is the key. Europe is not trying to win the tokenisation race by building the fastest chain. It is making sure that, whichever chain wins, the safest settlement asset in the euro area is available on it.
The implication for dollar stablecoins is direct. In wholesale euro markets, the argument that USDT or USDC are the only practical on-chain cash just got weaker. For euro stablecoin issuers, the message is more nuanced: retail and cross-border use cases remain open, but the high-value interbank market now has a public alternative.
What to watch
- Operating hours. A tokenised market that settles 8 to 4 on weekdays is not yet the 24/7 market tokenisation promised. Broader capability is expected with the ECB's Appia blueprint, due around 2028.
- Volumes. Launch-day participant lists are easy. The real test is whether primary issuance of tokenised bonds moves onto Pontes-connected platforms in 2027.
- The retail digital euro. Pontes is wholesale only. The retail pilot is scheduled for the second half of 2027, with possible issuance in 2029, subject to EU legislation.
Tokenised assets on-chain, with settlement still carrying private-money risk, was always an incomplete modernisation. Pontes closes that gap for Europe's wholesale market. Whether the market uses it is now the only open question.
FAQ: ECB Pontes Settlement Platform
What is Pontes?
Pontes is a European Central Bank service, live since 21 September 2026, that links market DLT platforms to the Eurosystem's TARGET Services. It lets DLT-based wholesale transactions settle in central bank money, either via cash tokens on the platform or directly in T2.
Who can use Pontes?
According to the ECB, Pontes is open to entities with T2 access, authorised central securities depositories and DLT settlement operators, overseen payment system operators, central counterparties and eligible credit institutions. Early participants reported at launch include Deutsche Bank, Santander and Clearstream.
Why does Pontes matter for tokenisation?
Tokenisation projects struggled with what the buyer pays with, since stablecoins and tokenised deposits carry private-money risk. Pontes lets tokenised securities settle in central bank money, which weakens the argument that dollar stablecoins are the only practical on-chain cash in wholesale euro markets.
What are Pontes' operating hours?
Pontes runs from 8:00 to 16:00 CET on business days. Broader capability is expected with the ECB's Appia blueprint, due around 2028.
Is Pontes the same as the digital euro?
No. Pontes is wholesale only, although Christine Lagarde described it as a digital euro made available for banks. The retail digital euro pilot is scheduled for the second half of 2027, with possible issuance in 2029, subject to EU legislation.